skip to content

ADHD and Money: Why Does Your Salary Vanish by the 15th?

Reading Time 9 mins

Key Takeways

• Money trouble with ADHD is usually an executive-function pattern (planning, memory, impulse control), not carelessness or a character flaw.
• Impulse buys, missed bills and avoided bank statements often feed shame and stress, which can make the pattern worse.
• Many other things can look like ADHD-related money trouble, including anxiety, burnout, and genuine financial strain, so a proper assessment matters.
• Systems that work with your brain (automation, friction, simple buckets, a weekly check-in) tend to help more than willpower.

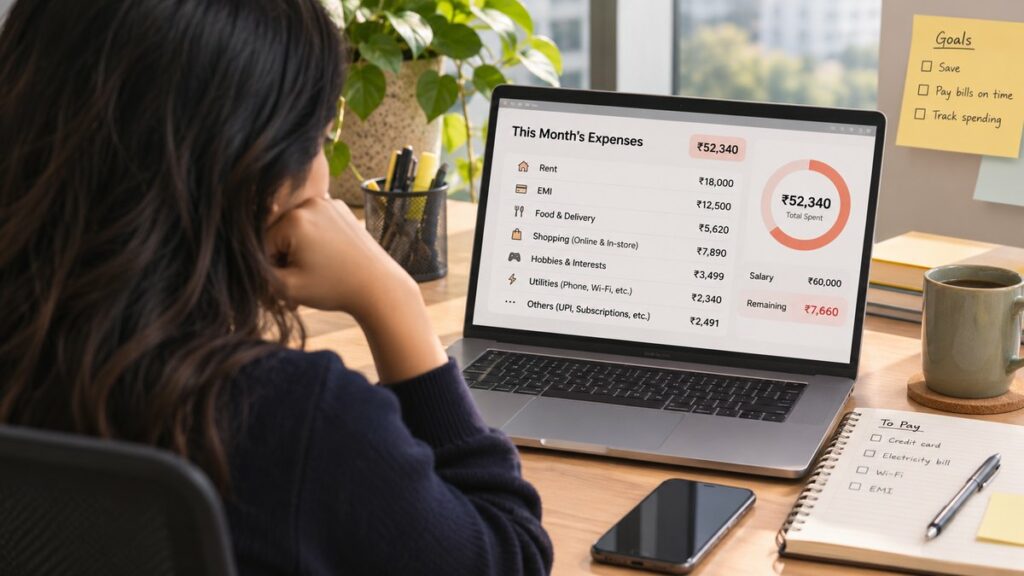
It is the 18th. Rent is paid, the EMI is due, and the salary is nearly gone. She cannot quite say where it went: a few UPI payments, a late-night Amazon cart, two missed bill reminders and a late fee. People tell her to "just make a budget," and she has started to believe she is simply bad with money.

If this sounds familiar, you are not alone, and it is probably not about discipline. In this article, we look at why ADHD and money struggles so often go together, what drives impulsive spending and missed payments, what this looks like in everyday Indian life, what else can look like ADHD-related money trouble, and what actually helps.

At Mitsu across our clinics in Mumbai, our team of mental health professionals who work with adults with ADHD we come across clients who have had a hard time managing their finances and who struggle with decision making hence impacting their overall quality of life.

Why ADHD and money struggles often go together

Managing money quietly asks for a lot: planning ahead, holding numbers in working memory, resisting a tempting purchase, remembering due dates, and sticking with a system for months. These are exactly the skills ADHD can make harder.

The relationship also runs both ways. ADHD can make money harder to manage, and financial stress can worsen focus, sleep, and mood, which can look like "more ADHD." And because many adults are undiagnosed, repeated money trouble is often the first thing they notice.

A note on balance: not everyone who overspends or forgets a bill has ADHD, and this article is not meant for self-diagnosis. Plenty of people struggle with money for many reasons.

Why is money so hard to manage with ADHD?

  1. The "Now" Brain and Impulse Spending

    ADHD brains tend to be drawn to immediate rewards. A purchase delivers a small hit of satisfaction right now, while the cost lands weeks later on a credit card statement. "I'll think about it later" sounds sensible, but later rarely arrives, because the item is already in the cart, the order is placed, and the next thing has caught your attention.

  2. Out of sight, Out of mind: missed bills and due dates

    Time blindness and forgetfulness mean a due date that felt far away can suddenly be three days ago. The result is late fees, credit card interest, and a familiar wave of shame. Many people with ADHD are not short of money on those days. The bill simply slipped out of mind.

  3. Retail therapy and emotional spending

    Shopping can lift a low mood, relieve boredom, or feel like a reward after a hard day. Food delivery apps, sale seasons and one-click checkout make this easy. The relief is real but brief, and the regret that follows can set up the next round of spending.

  4. Budget burnout

    Many people with ADHD have started a beautiful budgeting spreadsheet, colour-coded and perfect, and abandoned it within a week. Rigid systems demand constant upkeep and consistency, which is precisely where ADHD brains struggle. When the system fails, it is easy to conclude that you have failed. Usually, the system was the wrong fit.

  5. Hyperfocus purchases and abandoned hobbies

    A new interest arrives with intense energy: a full set of gear, the right courses, the best equipment. Then the spark fades, and the guitar, the camera, or the art supplies gather dust. This is not fickleness. It is how interest and reward often work in ADHD.

  6. Avoidance and financial anxiety

    For some, the hardest part is not spending but looking. Not opening the bank app or the credit card statement because it feels overwhelming. The longer it is avoided, the bigger and scarier it gets, so avoidance quietly makes things worse.

  7. Other contributors

    • Irregular income, such as freelance work or gig earnings
    • Pressure to "keep up" socially
    • Little or no financial education at home
    • Medication and treatment: if you are on or considering ADHD medication, please discuss any concerns about how it affects your routines with your prescribing doctor
    Does this sound like you?
    • You are unsure where your money went each month
    • You buy things you later forget you own
    • You avoid opening bank or credit card statements
    • You pay bills late even when you have the money
    • You start budgets with energy, then drop them within days
    • You feel guilt or shame whenever money comes up
    If several of these ring true, it may be worth speaking to a professional. A checklist is a starting point for reflection, not a diagnosis

What does this look like in everyday life?

• Frictionless payments. UPI, buy-now-pay-later and one-tap checkout make spending feel like it costs nothing in the moment, and festive sale seasons and big shopping events add to the pull.
• Heavy financial responsibilities. EMIs, supporting parents or siblings, and family expenses leave little room for error, so each slip feels more stressful.
• Social pressure. Weddings, gifting, and lifestyle upgrades come with expectations that are hard to opt out of.
• Silence and stigma. Money is often a taboo topic, and adult ADHD is still poorly understood, so these struggles tend to be blamed on "bad habits" or "lack of discipline."

How money stress feeds back into ADHD symptoms

Money worries do not stay in your bank account. They show up the next day as worry, poor sleep, low focus, irritability, and more avoidance. When you are stressed and tired, impulse control is harder, which makes the next unplanned purchase more likely.

The cycle often looks like this:
Impulse → regret → stress → lower self-control → impulse

Seeing the cycle can be a relief in itself. It shows that the problem is a loop you are caught in, not proof that something is wrong with you.

What the research says

Research on ADHD and money is still growing.
• Debt and late payments. A study of 544 adults (average age 35) found that ADHD symptoms were linked to a preference for immediate rewards, late credit card payments, higher card balances, personal debt, and shorter job tenures, even after accounting for age, income, sex, education and substance use. Hyperactive-impulsive symptoms explained more of these links than inattentive ones (read it here).
• Impulsive buying. A 2024 study in Clinical Psychology in Europe compared 225 adults with ADHD and 121 university students. The ADHD group showed more impulsive buying and a lower ability to delay gratification, and that ability appeared to explain part of the link (read it here).

What else can look like this?

Several things can look like ADHD-related money trouble, which is why symptoms alone cannot confirm ADHD:
• Anxiety, depression, trauma, burnout, and chronic stress
• Compulsive buying or other impulse-control difficulties
• Mood changes in the bipolar spectrum, which need professional assessment
• Genuine financial hardship, low income, or limited financial literacy
• Poor sleep, which affects impulse control and memory on its own

A proper assessment looks at your history, your day-to-day functioning, and other possible explanations. That is what makes the difference between guessing and getting the right support.

What helps: Gentle ways to make money easier

The aim is not to become a different person. It is to build systems that work with your brain, not against it.
• Automate the essentials. Set auto-pay for rent, EMIs and bills, and an auto-transfer to savings on salary day. If you do not have to remember, you cannot forget.
• Pay yourself first. Keep savings in a separate account so it does not look like spending money.
• Try the 24-hour rule. Move the item to a wishlist and wait a day before buying. Many urges fade by themselves.
• Add friction to impulse buying. Delete saved cards, log out of shopping apps, and unsubscribe from sale alerts.
• Keep the budget simple and visual. Two or three buckets (needs, savings, fun) beat a 20-line spreadsheet you will abandon.
• Do a weekly 10-minute money check-in. Same time, same cue, maybe with a cup of chai. Small and regular works better than big and rare.
• Consider individual therapy. Therapy can help with emotional spending, avoidance, shame, and building routines that fit your brain.
Be kind to yourself while trying these. Pick one or two, of the above. A system you actually use is worth more than a perfect one you do not.
• Consider individual therapy. Therapy can help with emotional spending, avoidance, shame, and building routines that fit your brain.
Be kind to yourself while trying these. Pick one or two, not all nine. A system you actually use is worth more than a perfect one you do not.

Signs it might be time to get support

It may help to reach out if:
• Money trouble continues despite your best effort
• Debt, late fees, or secret spending are affecting your peace of mind or relationships
• Shame, anxiety, or low mood keep returning around money
• You have always felt "wired differently" but could never explain why
Support can include an assessment, individual therapy, and, where medication is a question, a review with your doctor. A financial planner can help with the numbers; therapy can help with the patterns behind them. You do not have to sort it out alone, and you do not need to wait for things to reach a crisis point.

How Mitsu approaches this

At Mitsu across our clinics in Mumbai, we work with each person in a collaborative and tailored way. We begin with a careful assessment to understand your patterns and rule out other causes. We then offer individual therapy and psychiatric support and coping strategies that fit your work, goals, and daily life.

Care team illustration

Need support with what you're experiencing?

If something you've read here feels relevant to you, our care team can help you understand the right next step.

Let's chat

Share

Frequently Asked Questions

Why do people with ADHD spend money impulsively?

ADHD is linked with a stronger pull toward immediate rewards and difficulty pausing before acting. A purchase gives instant satisfaction, while the consequences feel distant. Emotions such as boredom or stress can add to this. It is a pattern of how the brain handles reward and impulse control, not a lack of character.

Why do I forget to pay bills even when I have the money?

Remembering a due date depends on working memory, time awareness and follow-through, all of which can be affected by ADHD. A bill can slip out of mind even when the money is there. Auto-pay, calendar reminders and a weekly check-in can take the memory load off you.

Is it ADHD or just poor money management?

Only a qualified professional can tell. Anxiety, depression, burnout, compulsive buying, poor sleep, and real financial hardship can all look similar. A good assessment looks at your history and daily life, and considers other explanations, rather than relying on a quiz or a single symptom.

How can I budget if I have ADHD?

Keep it simple and automatic. Use two or three spending buckets rather than detailed categories, automate bills and savings, add a short weekly check-in, and allow some guilt-free fun money. If a method feels like a chore after two weeks, change the method, not yourself.

We’re here to help

Share your details and our team will call you shortly.

Thank you - we’ve received your request

Our team will call you shortly to help you get started